Welcome to the latest edition of Cox Automotive's Insight Quarterly, analysing the forces shaping the UK automotive market during the final quarter of 2026.
Drawing on proprietary data, market intelligence and insight from across the new, used and electric vehicle sectors, this report looks beyond the headline figures to explore the trends that will define the market into 2027.
At first glance, the market appears to be in robust health. New car registrations have continued to outperform expectations, electrified vehicles now account for more than half of all new registrations, and the used vehicle sector has demonstrated remarkable resilience despite a growing influx of supply. Taken together, these results paint a picture of a market that has adapted well to economic uncertainty and changing consumer behaviour.
However, as this quarter's analysis demonstrates, the underlying dynamics of that growth are changing rapidly. While registrations continue to rise, much of that expansion is concentrated among a relatively small number of manufacturers, most notably Chinese brands, whose influence on the UK market has grown at an unprecedented pace. In just a few years, they have moved from niche challengers to major market participants, reshaping competition, accelerating electrification and challenging long-established assumptions around brand loyalty, pricing and market share.
The new car market remains central to this transformation. Increased competition, wider consumer choice and continued growth in electrified vehicle sales have supported registrations throughout the year. Yet the industry's challenge is no longer simply generating demand. Manufacturers, retailers and funders must now contend with the longer-term implications of a more crowded market, increasing pricing pressure and greater uncertainty around future residual values. As more new entrants establish themselves, attention is shifting from volume growth towards the sustainability and profitability of that growth.
These developments are also beginning to influence the used vehicle market. Despite larger-than-expected volumes entering circulation, demand has remained resilient and vehicle values have largely held up. Perhaps most notably, used EV performance has continued to improve, with stronger conversion rates and a narrowing residual value gap relative to internal combustion engine vehicles. However, the market is entering a new phase where overall depreciation may become less important than the growing divergence between individual brands, models and powertrains. As supply continues to diversify, precision in pricing, stock selection and risk management will become increasingly important.
Looking ahead, policy and regulation are likely to play as significant a role in shaping market outcomes as consumer demand itself. The outcome of the ongoing ZEV Mandate review, future trade policy decisions and evolving support for electrification all have the potential to alter market dynamics over the coming years. Against a backdrop of increasing competition and technological change, the need for clarity and long-term confidence has rarely been greater.
The key message from this quarter is that growth alone no longer tells the full story. Today's automotive market is being shaped by a powerful combination of electrification, regulatory change and new competitive forces. In this environment, success will depend not only on the ability to grow, but on the ability to anticipate how the market itself is evolving and adapt accordingly.
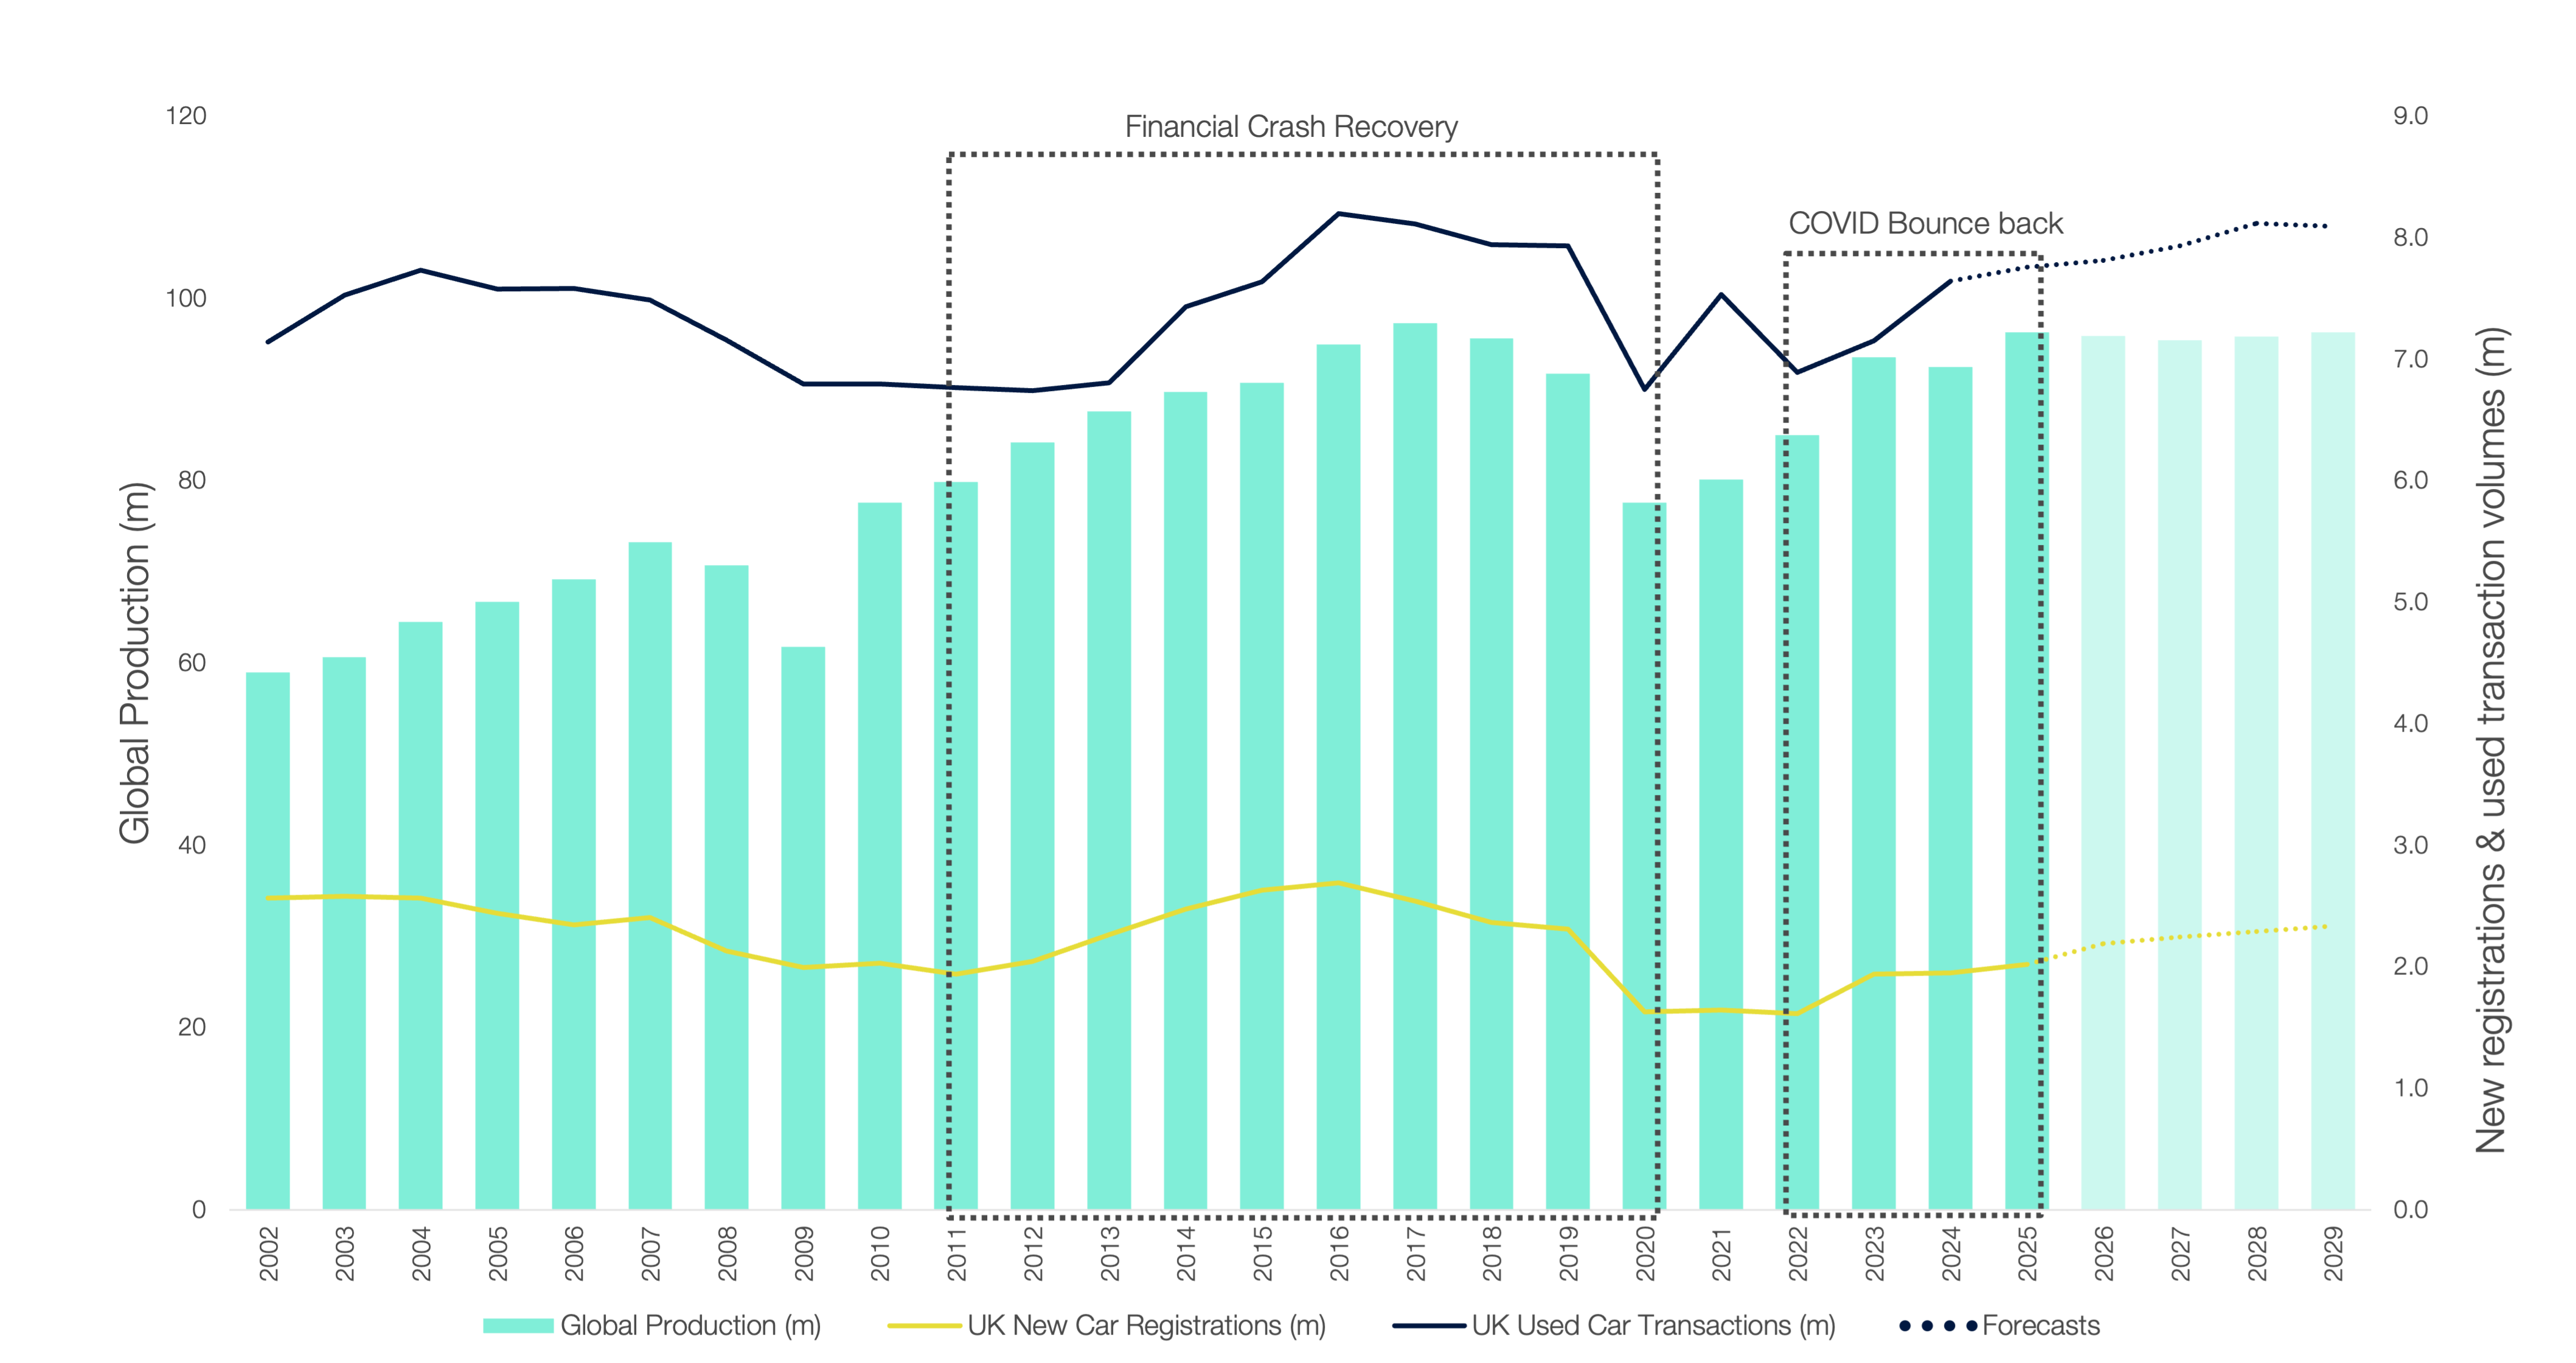
New & Used Sales vs. Global Production Volumes
Cox Automotive