EV car insurance: Costs, coverage, and tips for UK buyers

Understanding electric vehicle insurance is a key part of buying and owning a zero-emissions car. In this guide, we explain how EV insurance differs from cover for petrol or diesel cars, what determines quotes and pricing, and what to look out for when choosing a policy.
The UK's electric vehicle sector continues to grow, with almost 2.1 million EVs now in nationwide use.
As adoption soars, many drivers are researching EV ownership costs to understand how switching could impact their budgets. Perceptions of high costs remain a significant barrier as nearly two in three UK drivers think owning an EV is more expensive than a petrol or diesel car. Insurance is at the centre of these concerns.
But how much does electric car insurance truly cost, and what affects the price you pay? This guide explores how EV insurance works, the factors influencing premiums, and how to get the best value policy.
Key takeaways
- EV insurance works just like petrol and diesel car insurance, but policies often include extra considerations.
- On average, insuring an EV currently costs slightly more than an ICE vehicle.
- The most important policy details include battery and charger cover, plus access to EV-certified repairers.
- You can save on EV insurance costs by comparing multiple quotes and holding a strong no-claims record.
- Thanks to lower running and energy costs, EVs can still be cheaper to own despite higher insurance premiums.
EV insurance in the UK: How it works
Just like insuring a petrol or diesel car, EV insurance in the UK is a legal requirement for you to drive your car on UK roads. The three main types of car insurance cover apply to electric vehicles.
Types of car insurance coverage for electric and ICE vehicles include:
Third-party only
Third-party insurance covers the cost of damage or injury to other people and vehicles in an accident you’re at fault for. It doesn’t cover the cost of repairing your own vehicle. It also doesn’t cover you if your car is stolen, sets on fire, or is vandalised.
Third-party, fire and theft
Just like third-party only insurance, third-party, fire and theft insurance covers the other person and their vehicle involved in an accident you’re at fault for but doesn’t cover you or your own vehicle. This type of policy does cover your vehicle being stolen or setting on fire.
Fully comprehensive
Comprehensive cover is the highest level available.
This type of insurance policy covers the damage repair costs for all vehicles involved in an accident, including your own – even if you’re found at fault. It also usually covers theft of your vehicle, fire damage and vandalism.
How much does EV insurance cost?
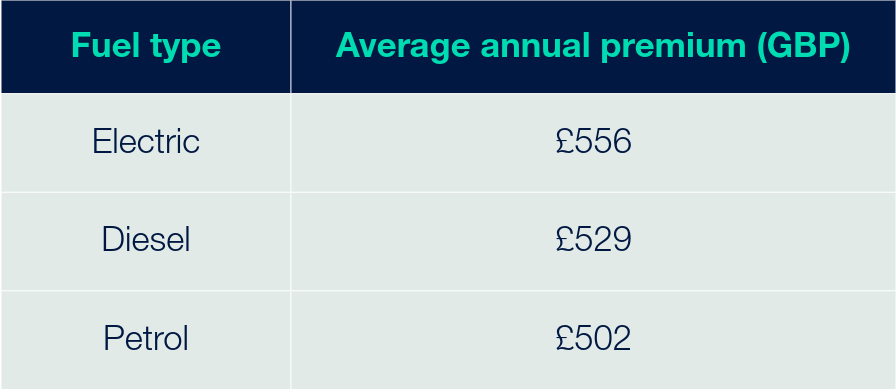
Compared to ICE cars, insurance costs for EVs tend to be higher on average.
According to the latest data from MoneySuperMarket, the average annual premium for EV insurance in 2026 is £556. That’s just 5% more than the average diesel car premium, but around 10% higher than annual cover for a petrol vehicle.
EV insurance costs may also vary by hundreds of pounds according to the make and model you choose. Smaller, urban EVs are likely to be cheaper to insure than luxury electric SUVs or those with extremely powerful batteries.
What factors affect EV insurance premiums?
Insurance is all about risk. Several distinct factors influence premiums for electric vehicle car and van insurance in the UK, and these may differ from those typically associated with petrol and diesel vehicles.
EV-specific considerations include:
- Cost of EV battery replacement or repair, and the requirement for battery-specific coverage (in EVs, the battery cost accounts for a significant chunk of the vehicle’s value)
- Cost of breakdown and recovery for electric vehicles, and availability of local repair specialists
- Additional equipment required for EVs, like charging cables
- Advanced safety features of electric vehicles, which may lower the risk of theft or accidental damage
What else influences the cost of car insurance?
Although considerations unique to EVs may have the greatest impact on insurance costs, there’s much more to deciding the price. Across all fuel types, insurance premiums are heavily influenced by the car itself, including through factors such as:
- The purchase price and market value of the car
- Repair costs and trends associated with the model
- The age and mileage of the car
- Your home address and typical driving habits, including where you park
- Your age and driving experience
Don’t let higher average insurance premium costs put you off choosing an electric vehicle. Even with other ownership costs considered, electric vehicles can still be significantly cheaper to run overall than petrol cars.
Choosing the right EV insurance policy
While all motor insurance policy documents remain largely the same in structure, there are some key differences that electric car owners need to watch out for.
Thanks to their specialist parts and components, EVs come with different repair and recovery costs. And when you also factor in road tax and charging, it's worth having the right level of electric car insurance cover to suit your needs as a driver.
What to consider when choosing your EV insurance policy
Level of battery cover
Electric car batteries can cost thousands of pounds to replace and are typically the most expensive part of the vehicle. That’s why it's important to check the battery-specific terms in your electric car insurance policy. The level of battery replacement or battery damage repair cover you want may not be included as standard.
Occasionally, manufacturers may sell you the car but lease you the battery to reduce the car’s purchase price. If your battery is leased, check whether the insurer will deal directly with the battery leasing company, and whether your leased battery is covered appropriately.
Charging equipment
Check if your policy includes cover for damage to your home charging point, cable or even public hardware if you’re charging on the go.
Some EV insurance policies may also include electric charger liability cover. This protects you if someone trips over or is injured by your home charging setup, for example.
Repair requirements and stipulations
Depending on your EV purchase or lease agreement, you may be limited to certain manufacturer-approved garages. You may also find that your electric vehicle car insurance policy may stipulate how and where your car can be repaired under their cover (typically EV-certified garages).
Ensure you have those approved repair specialists in your area, to keep your travel costs down if your car needs repairing.
Breakdown cover and EV-specific recovery
Breakdown cover is widely available as an EV car insurance add-on, but this doesn't always mean you'll get roadside repairs or an electric courtesy car.
If you break down or are involved in a car accident, it's worth knowing if your EV's insurance policy covers:
- EV rescue
- Roadside charging
- The cost of being towed to the nearest public charger
- Electric hire car cover
- Access to specialist EV service providers
Policy details and optional extras
As with any car insurance, you’ll want to check that you’re happy with policy basics.
Alongside the general type of cover you have (like comprehensive or third party) and the excess you'll pay if you need to make a claim, optional extras typically include:
- European cover, for example for family holidays
- Cover for commuting and business travel
- Whether or not you'd like to protect your no-claims bonus
- Legal expenses protection
- EV hire car while yours is at the garage
Tips for lowering the cost of EV insurance premiums
Just like with any insurance policy, there are things you can do to help lower the cost of your EV insurance premium.
Compare car insurance for EVs from multiple providers
Whether you’re looking for your first EV insurance policy or your existing policy is ending, shop around and make a policy comparison from different insurers.
Don’t just look at the price. Make sure you check what’s covered on the policy, including the excess, to get the best value and the most appropriate cover for what you need.
Consider home charging location safety
With any type of vehicle, if your car is parked off-street and secured overnight (for example, on a private driveway or in your garage), then the risk of theft, damage or vandalism is much lower.
With an EV, you will need to consider where you install your home charging point. This promotes your personal safety and helps to keep your car at a low risk when it’s parked up and charging.
Maximise no-claims discounts
No-claims discounts can sometimes save hundreds of pounds on car insurance for electric vehicles and work the same as petrol or diesel car insurance policies. They provide you with a discount based on the number of consecutive years you’ve held a policy and not made a claim.
No-claims discounts apply no matter what type of car you’ve insured, whether that’s petrol, diesel, electric or hybrid, as long as it’s a like-for-like policy (e.g. your own private car insurance rather than commercial use) and not from a different type of vehicle like a van.
Use telematics or pay-as-you-drive schemes
Telematics insurance, also known as black box insurance, uses tech like a smartphone app or a small box fitted to your vehicle to monitor your driving behaviour.
With telematics car insurance, insurers can check in real-time how safe your driving is. They can analyse various factors such as:
- How often you exceed the speed limit
- How often you need to brake quickly
- How you handle the car while steering
This means the insurer has more personalised data on your risk factors as a driver, and therefore how likely you are to need to make a claim on the policy.
As well as encouraging safer driving habits, this can help to lower your premiums at renewal, and sometimes even lead to refunds partway through your policy.
Check EV insurance customer reviews
Finally, personal recommendations matter when it comes to electric car insurance.
By learning about recent experiences from experienced EV drivers, you can gauge the level of service and support from each provider. Previous customer reviews could also provide valuable insight into the best car insurance for your specific make and model of EV.

EV insurance in perspective
On the whole, EV car insurance in the UK works much like insurance for petrol or diesel cars, with a few key differences in coverage.
Insurance premiums for EVs are currently higher on average because parts and repair costs are higher. But as EV adoption rates increase, there’s a good chance that these prices will fall in future to be more in line with other types of cars.
For now, there are plenty of things you can control that will influence what you pay, ranging from the value of your EV to the type of policy you choose. Daily habits, including how and where you park and charge your electric car, can also affect your premium.
Even with a higher average insurance cost, electric car ownership costs are still lower on average than petrol or diesel cars. If you want to learn more about the cost of owning an electric vehicle, look at our guides on EV charging costs and current EV grants.
FAQs: Choosing car cover for your EV
What is the best electric car insurance cover?
Comprehensive car insurance offers the highest level of protection for your electric car. It covers accidental damage to your vehicle and costs towards third-party liabilities, including injuries or damage to property.
Optional extras for comprehensive car insurance further increase flexibility, keeping you, your passengers and your belongings protected.
Is it more expensive to insure an electric car or van?
Electric van insurance is generally more expensive than the equivalent cover for an electric car. This is due to various factors, including their generally larger battery packs, frequent commercial use, and higher replacement value.
What is an insurance group?
Each new car or van model – EV or ICE – is assigned an insurance group, decided based on factors like value and performance.
This reflects a predicted level of risk and can also have a big impact on what you pay. According to data from MoneySuperMarket, the cost difference between vehicles in Group 1-10 and those in Group 41-50 can be as much as £400 a year.
How is telematics insurance calculated?
Typically, a telematics box is fitted to your car to record your mileage automatically, and your policy will either be on a pay-per-mile basis or a total mileage limit in a year.
Conversely, pay-as-you-drive electric car insurance policies focus less on your general behaviours as a driver and more on how far you travel – the less you use the car, the less insurance you pay.
Does comprehensive cover include motor legal protection?
No. Motor legal protection, also known as motor accident protection, is usually available as an optional extra to your electric car insurance.
In the event of an accident that wasn't your fault, it covers any necessary legal costs required to recover losses that were not covered under your car or home insurance policy. These are known as uninsured losses.
Does standard car insurance include personal accident cover?
Typically, no. But whether you've chosen third-party or comprehensive cover for your electric car, it may be available as an optional extra. For an annual fee, this provides you with additional protection if you can't claim personal injury compensation, for example if you were found at fault.
What is an uninsured driver promise?
The uninsured driver promise provides peace of mind if your electric car is damaged by an uninsured third-party. In the event of an accident or collision, this means you can make a claim for repairs and often still protect your no-claims bonus.
EV service guide: Costs, checks, and tips for owners
Answer your biggest EV servicing FAQs, find guides to EV servicing costs, and learn new EV best practices.
Electric vehicle costs: What to expect over 5 years
A breakdown of all the associated costs and potential savings associated with an EV.